 admin
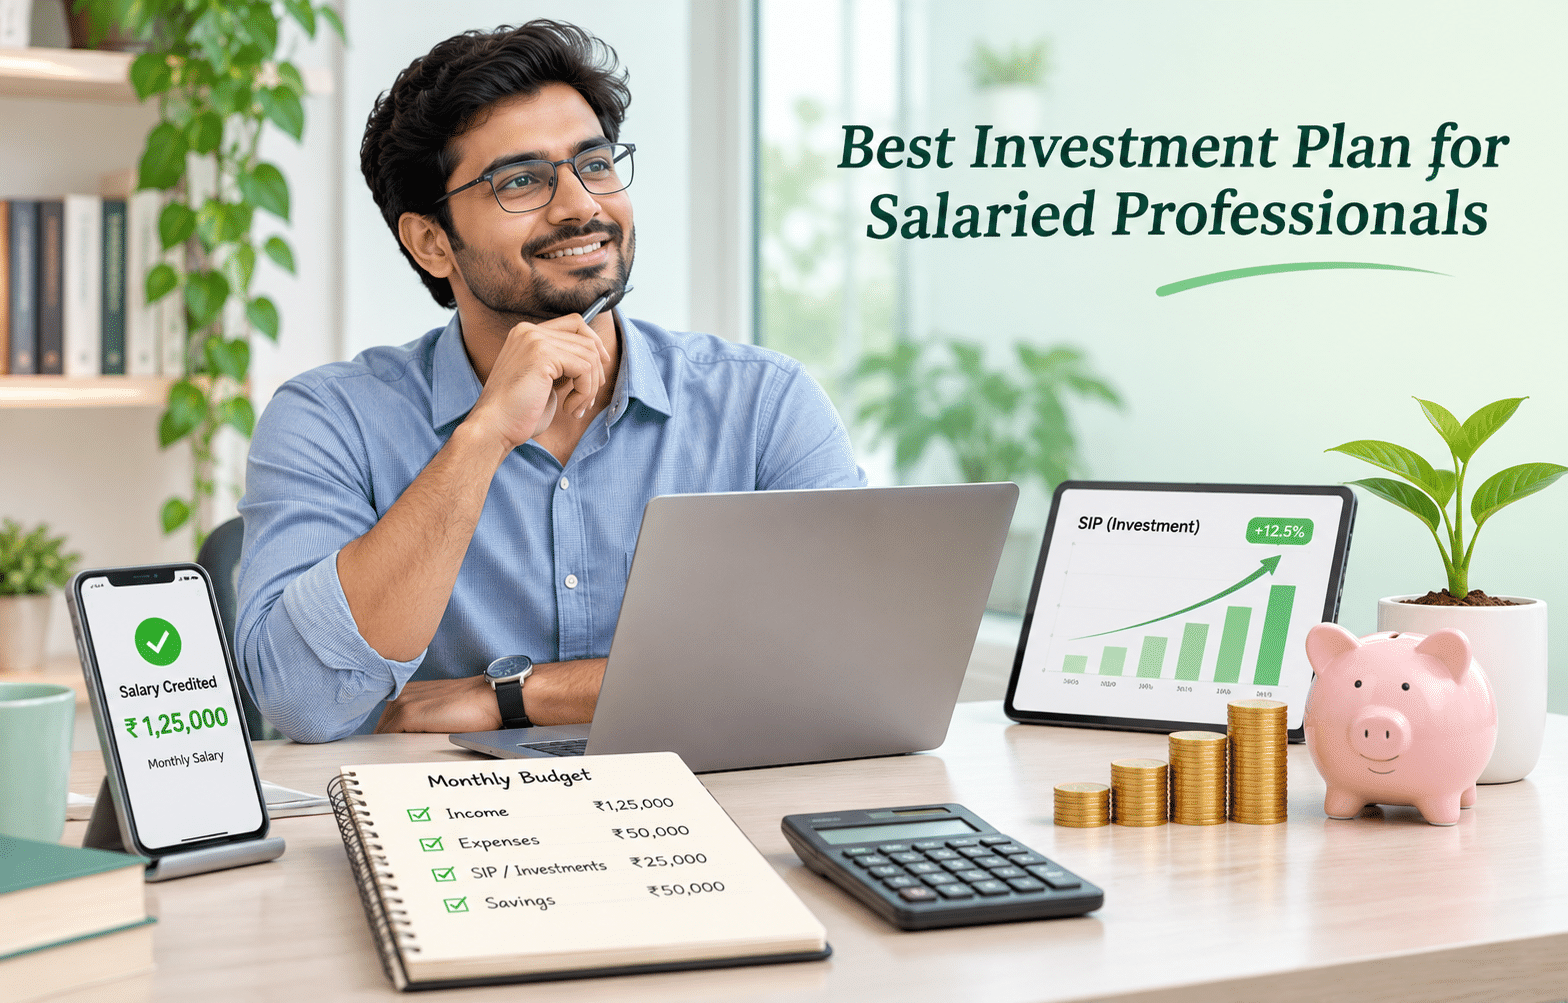
It’s the 1st. Salary lands, and you feel rich for about six hours.
Then rent goes out. The EMI goes out. The electricity bill, the grocery run, the “just one” weekend dinner that turned into ₹3,000. By the 20th you’re checking your balance and wondering what happened.
Somewhere in all of this, investing keeps slipping to “next month.” Sound familiar?
First, you’re not behind. You don’t need more income or more financial jargon. You need a plan, and a simple one. Let’s build it.
Why “I’ll Start Someday” Costs You More Than You Think
A salary is steady, but it doesn’t beat inflation on its own. Prices rise every year, and money sitting idle in a savings account quietly loses buying power.
The good news is that you don’t need a big income to fix this. You need time and consistency.
Here’s an example. Assume a 12% annual return, which is not guaranteed but is a reasonable long-term expectation for equity.
- Riya starts a ₹5,000 monthly SIP at 25 and continues until 60. She ends up with roughly ₹3.2 crore.
- Karan starts a ₹10,000 monthly SIP at 35 and continues until 60. He ends up with roughly ₹1.9 crore.
Karan invests double the monthly amount and still finishes well behind, because Riya gave her money ten extra years to grow.
If you’re reading this at 32, 38 or 45, that’s not a reason to quit. It’s a reason to start this week, not next year.
Step 1: Get Your Budget in Order
Before picking any fund, understand what you spend on. A basic budget would be:
- 50% on needs (rent, EMIs, grocery, bill payments)
- 30% on wants (eating out, shopping, traveling, subscriptions)
- 20% on savings and investments
If 20% is too much to save currently, start saving 10%. Even that small amount you invest will work better than that large amount you just plan to invest.
Step 2: Build Your Safety Net First
This is the step most people miss, but one which will save your investments down the line.
Emergency funds: Maintain between 3 and 6 months worth of expenses in either a savings account or a liquid fund/short-term FD. In case you are the sole breadwinner in your family or have dependents, aim for 6 months. Without this financial buffer, any job loss or health emergency means breaking your investments at the most inopportune time.
Medical insurance: Relying only on the medical insurance provided by your employer is not a good idea because once you lose your job, you also lose this coverage. Get a personal medical insurance plan at an early age because premiums are low and you do not face the issue of pre-existing conditions here.
Term Insurance: If there are people dependent on your income, go for a pure term plan and not the investment+insurance plans.
Also Read: HOW TO BEGIN INVESTING WITH ONLY ₹500 PER MONTH
Step 3: Pick Your Investments
Here are some possible investment instruments that work professionals in India could use.
Systematic Investments in Mutual Funds (SIP)
A Systematic Investment Plan will allow you to make regular monthly investments – as little as ₹500. An index or flexi-cap fund is a good option to start with. Leave it for 10 to 15 years, and not 10 to 15 months.
Equity-Linked Savings Scheme (ELSS)
It is a tax-savings instrument under Section 80C and comes with market-linked growth. It has a 3-year lock-in, which is the shortest of all 80C instruments.
Public Provident Fund (PPF)
This is a government-backed scheme with guaranteed returns and no taxation at maturity. It matures after 15 years, and its interest rate is revised every quarter by the government.
National Pension System (NPS)
It is a retirement-oriented scheme. Under the old tax regime, you can claim an additional deduction of ₹50,000 over and above the ₹1.5 lakh 80C limit under Section 80CCD(1B). The problem with it is that some portion of this money will remain locked until retirement.
Fixed Deposits
It works very well for short-term financial goals and also as an emergency fund. The only caveat is that the interest earned will be completely taxable as per your income slab.
Each of these instruments cannot do it all. But combining them according to your needs can be very effective.
A Quick Word on Tax Regimes
Almost all of the tax benefits mentioned above – except Section 80CCD(1B) – are not available in the new tax regime. In the new tax regime, the slabs are lower, but there is no such deduction. Instead of doing some investment purely “for saving tax,” calculate which tax regime suits you the best. Don’t choose a product solely on the basis of deduction. First decide which regime is better, and then make an investment that saves tax.
What a Starter Plan Could Look Like
Say you earn ₹60,000 a month take-home. This is an example, not advice:
| Where it goes | Monthly amount |
| Needs (rent, EMI, bills, groceries) | ₹30,000 |
| Wants | ₹18,000 |
| Investing and saving | ₹12,000 |
The ₹12,000 could be split into a ₹5,000 equity SIP, ₹3,000 in PPF or NPS, ₹2,000 in ELSS (if you’re on the old regime), and ₹2,000 towards building your emergency fund until it’s complete. Once the emergency fund is done, redirect that ₹2,000 into your SIP.
Starting Late? Here’s How to Catch Up
If you’re starting in your late 30s or 40s, you can’t rely on time alone, so lean on these three levers:
- Invest a higher percentage. Aim for 25 to 30% of your income if you can manage it.
- Step up your SIP every year. Raising it by 10% annually makes a huge difference over time.
- Cut the leaks. Unused subscriptions, expensive loans and lifestyle creep all eat into what you could be investing.
You can’t get those lost years back, but you can absolutely close much of the gap.
Mistakes That Quietly Hurt Your Wealth
- Waiting for the “perfect time” to begin
- Investing with no goal or timeline in mind
- Remembering tax planning only in March
- Putting everything into one asset class
- Stopping your SIPs the moment the market falls
- Buying a product because a friend or relative swore by it
That fifth one deserves attention. Market dips are when SIPs work hardest for you, because you’re buying more units at lower prices. Stopping then is like leaving a sale because the prices dropped.
How to Make It Automatic
Willpower is unreliable, and automation isn’t.
- Fix your SIP schedule 2-3 days after your salary credit so that you don’t get a chance to use the funds.
- When there is an increment in your salary, increase your SIP amount before the additional income becomes a part of your expenses.
- Just once a year check your investments, not everyday.
It’s just one practice that can give you lakhs or even crores to your retirement fund.
Final Thoughts
A good investment strategy is not all about finding out which fund is currently the most profitable or being on top of market timing strategies. A good investment strategy is all about making a start, sticking to it, and reviewing it once a year based on changes in your income and financial aspirations.
FinancePuff believes that financial planning for salaried individuals should be straightforward, not overwhelming.
FAQs
1. What percent of my salary should I invest?
Invest roughly 20% of your salary, even if it looks like a very tough target to meet in the beginning. Start with 10%, and increase it once your income goes up. What counts is the practice itself.
2. What should be the investment strategy for a beginner investor?
Make an emergency fund first, and then start a small SIP in a diversified equity fund. Once you get used to it, you can include tax-saving investment vehicles like ELSS and PPF.
3. Which investment scheme – NPS or PPF – is better for my future retirement?
These two schemes have different objectives and can be used by one person together. PPF offers safer investment with guaranteed returns that will also be tax-free. NPS is a market-based investment instrument with additional tax deductions under the old tax system and partial lock-in until retirement.
4. What are the most frequent mistakes made by salaried investors?
Starting investments only when it’s convenient, investing all funds in one product, and interrupting regular SIPs in case of market falls.
5. Can I start my investments if I earn only ₹25,000 per month?
Yes, any SIP from ₹500 to ₹1,000 per month will be enough.
6. How often should I update my investment plan?
Once a year is sufficient; just check your objectives, rebalance your portfolio in case of one asset dominating in your portfolio, and raise your SIP each year after your salary increment.
7. Is there still a chance to become rich when investing starts at the age of 40?
Yes, although you have to invest much more aggressively. Raise SIP, avoid unnecessary debts, and be realistic with your goals.
8. Should I repay my loans before starting my investments?
It’s better to start with repaying loans with the highest interest rate (credit cards, etc.) because such expenses usually exceed investment gains. In the case of a low-interest loan (for example, a housing loan), you can invest and repay your loans at the same time.